It’s a Mixed Bag
If one phrase summarizes the current state of the paper market, it is consistent uncertainty. It seems like this has been the case for the last couple of years.
The mail marketing industry is showing strong resilience as it navigates a complicated mix of tariffs, imports, planned mill downtime, postal rate increases, rising transportation costs, and ongoing shifts in supply and demand. While there have been periods of relative stability, the market remains difficult to predict.
Overall, graphic paper demand continues to face structural pressure. This year, the story has been rising diesel prices and mill capacity adjustments combined to influence pricing and overall paper availability.
New Fuel Surcharge Dominates the Industry News
Nearly every major paper manufacturer has announced some form of fuel or freight surcharge. The surcharge will likely translate to a 1.5 – 2% increase in overall paper costs. The surcharge will apply to new orders moving forward if diesel prices do not decrease.
With the mid-term elections now determined, there are new pathways for diesel prices to start showing a steady decline, but we do not expect prices to drop quickly enough to generate substantial reductions in overall delivery costs over the next 12 months.
Uncoated Freesheet
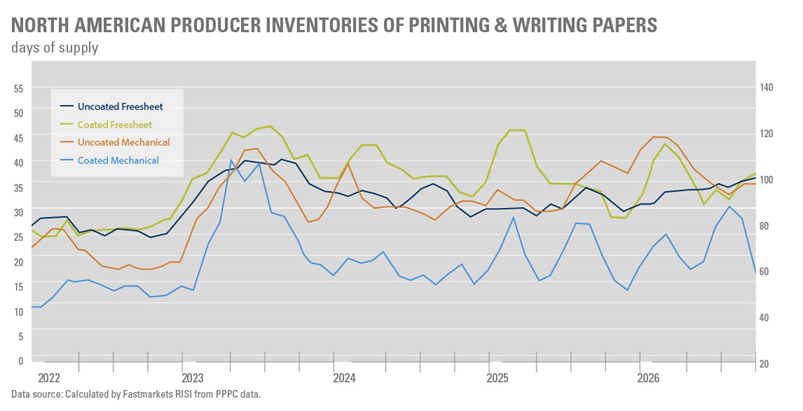
The North American uncoated freesheet (UFS) market is slowing. Domestic mills’ shipments declined 4% year-over-year in August, contributing to a drop in seasonally adjusted operating rates from an average of 92% in June and July to approximately 86% in August. On a non-seasonally adjusted basis, operating rates were more stable, remaining just below 90%, consistent with what we saw in the past four months.
The Canadian tariffs will not affect uncoated offerings at this time.
Imports & Demand Outlook
U.S. uncoated free sheet (UFS) imports remained elevated through the summer, although shipments from Brazil declined significantly following the implementation of higher tariffs.
Summer imports are expected to limit the decline in North American UFS demand to approximately 2% in 2026. However, this strength is likely temporary. Continued structural demand weakness, combined with the potential drawdown of excess inventories, could lead to a more significant decline in the fourth quarter.
Looking further ahead, Fastmarkets projects imports to decline from an annualized rate of approximately 1.1 million tons during the second and third quarters of 2026 to roughly 770,000 tons in all of 2027. This represents a substantial reduction in import volume and will be an important factor in determining domestic mill operating rates and overall market conditions.
Market inventories remain high, which should limit the potential for significant market tightening during Q4, even with the extended Eastover mill outage.
With demand continuing to decline and imports expected to remain strong, a potential restart of the Chillicothe mill’s uncoated freesheet production could put additional downward pressure on prices in 2027.
Mill Updates
Syvamo’s Eastover mill is scheduled for an extended maintenance outage in Q4 2026, expected to last for roughly 50-60 days. The outage will remove roughly 50,000 tons per month of UFS production from the market. Domestic mills appear to have prepared for the outage by building inventory in advance. Between domestic producers, importers, and buyers, the market appears to have built sufficient inventory to help manage the temporary production loss. However, inventory levels and how quickly they are drawn down will be important factors to watch over the coming months.
US Paper Mill plans to restart paper production at its Chillicothe mill by the end of the year. The restart is expected to focus on PM12, which previously had roughly 220,000 tons of annual UFS capacity. It remains unclear what products will be produced with the reopening.
International Paper plans to invest approximately $250M to convert PM16 at its Riverdale Mill from uncoated paper production to containerboard.
Twin Rivers in Maine launched a new coated freesheet #3 gloss grade from 45# to 70# text called Snowbrite.
UPM-Sappi JV has a provisional EU decision date of 12/9/26. This may affect future paper imports from Europe, with potential pricing ramifications and reduced supply.
Sustana was acquired in Q4 by Hivest Capital partners with Kevin Richards as CEO.
Sustana has announced the following product name changes:
- Sustana Hitech -> Sustana Opaque Digital
- Sustana Hitech Inkjet -> Sustana Opaque Digital Jet
Despite the evolving tariff situation, opportunities for improved pricing on European imports remain. By planning ahead and ordering 12 weeks prior to your press date, you can take advantage of meaningful cost savings.
Coated Papers
Demand for coated freesheet (CFS) is beginning to soften following a stronger first half of 2026. July and August shipments were down 12% compared with the first-half average, signaling that the market may be losing some of its earlier momentum.
Sappi announced a price increase of $25/ton for Spectro, Spectro Digital, and Spectro Indigo effective November 23rd, 2026. No other recent price increases have been announced.
Operating rates are expected to remain near 85% through the end of 2026, with the potential to increase toward 87% in 2027 if import volumes decline.
Final Thoughts
The paper market continues to navigate complex pressures. As we move into 2027, demand is expected to weaken further, but that does not necessarily mean paper prices will follow. Changes in import volumes, mill capacity, and operating rates will play equally important roles in determining market conditions.
SPC’s recommendation is to stay informed, plan ahead, and maintain flexibility as the market continues to evolve. We will continue to monitor any further updates to help navigate what remains a consistently uncertain market.